The news
 Apple Pay has launched in
 India. Eligible
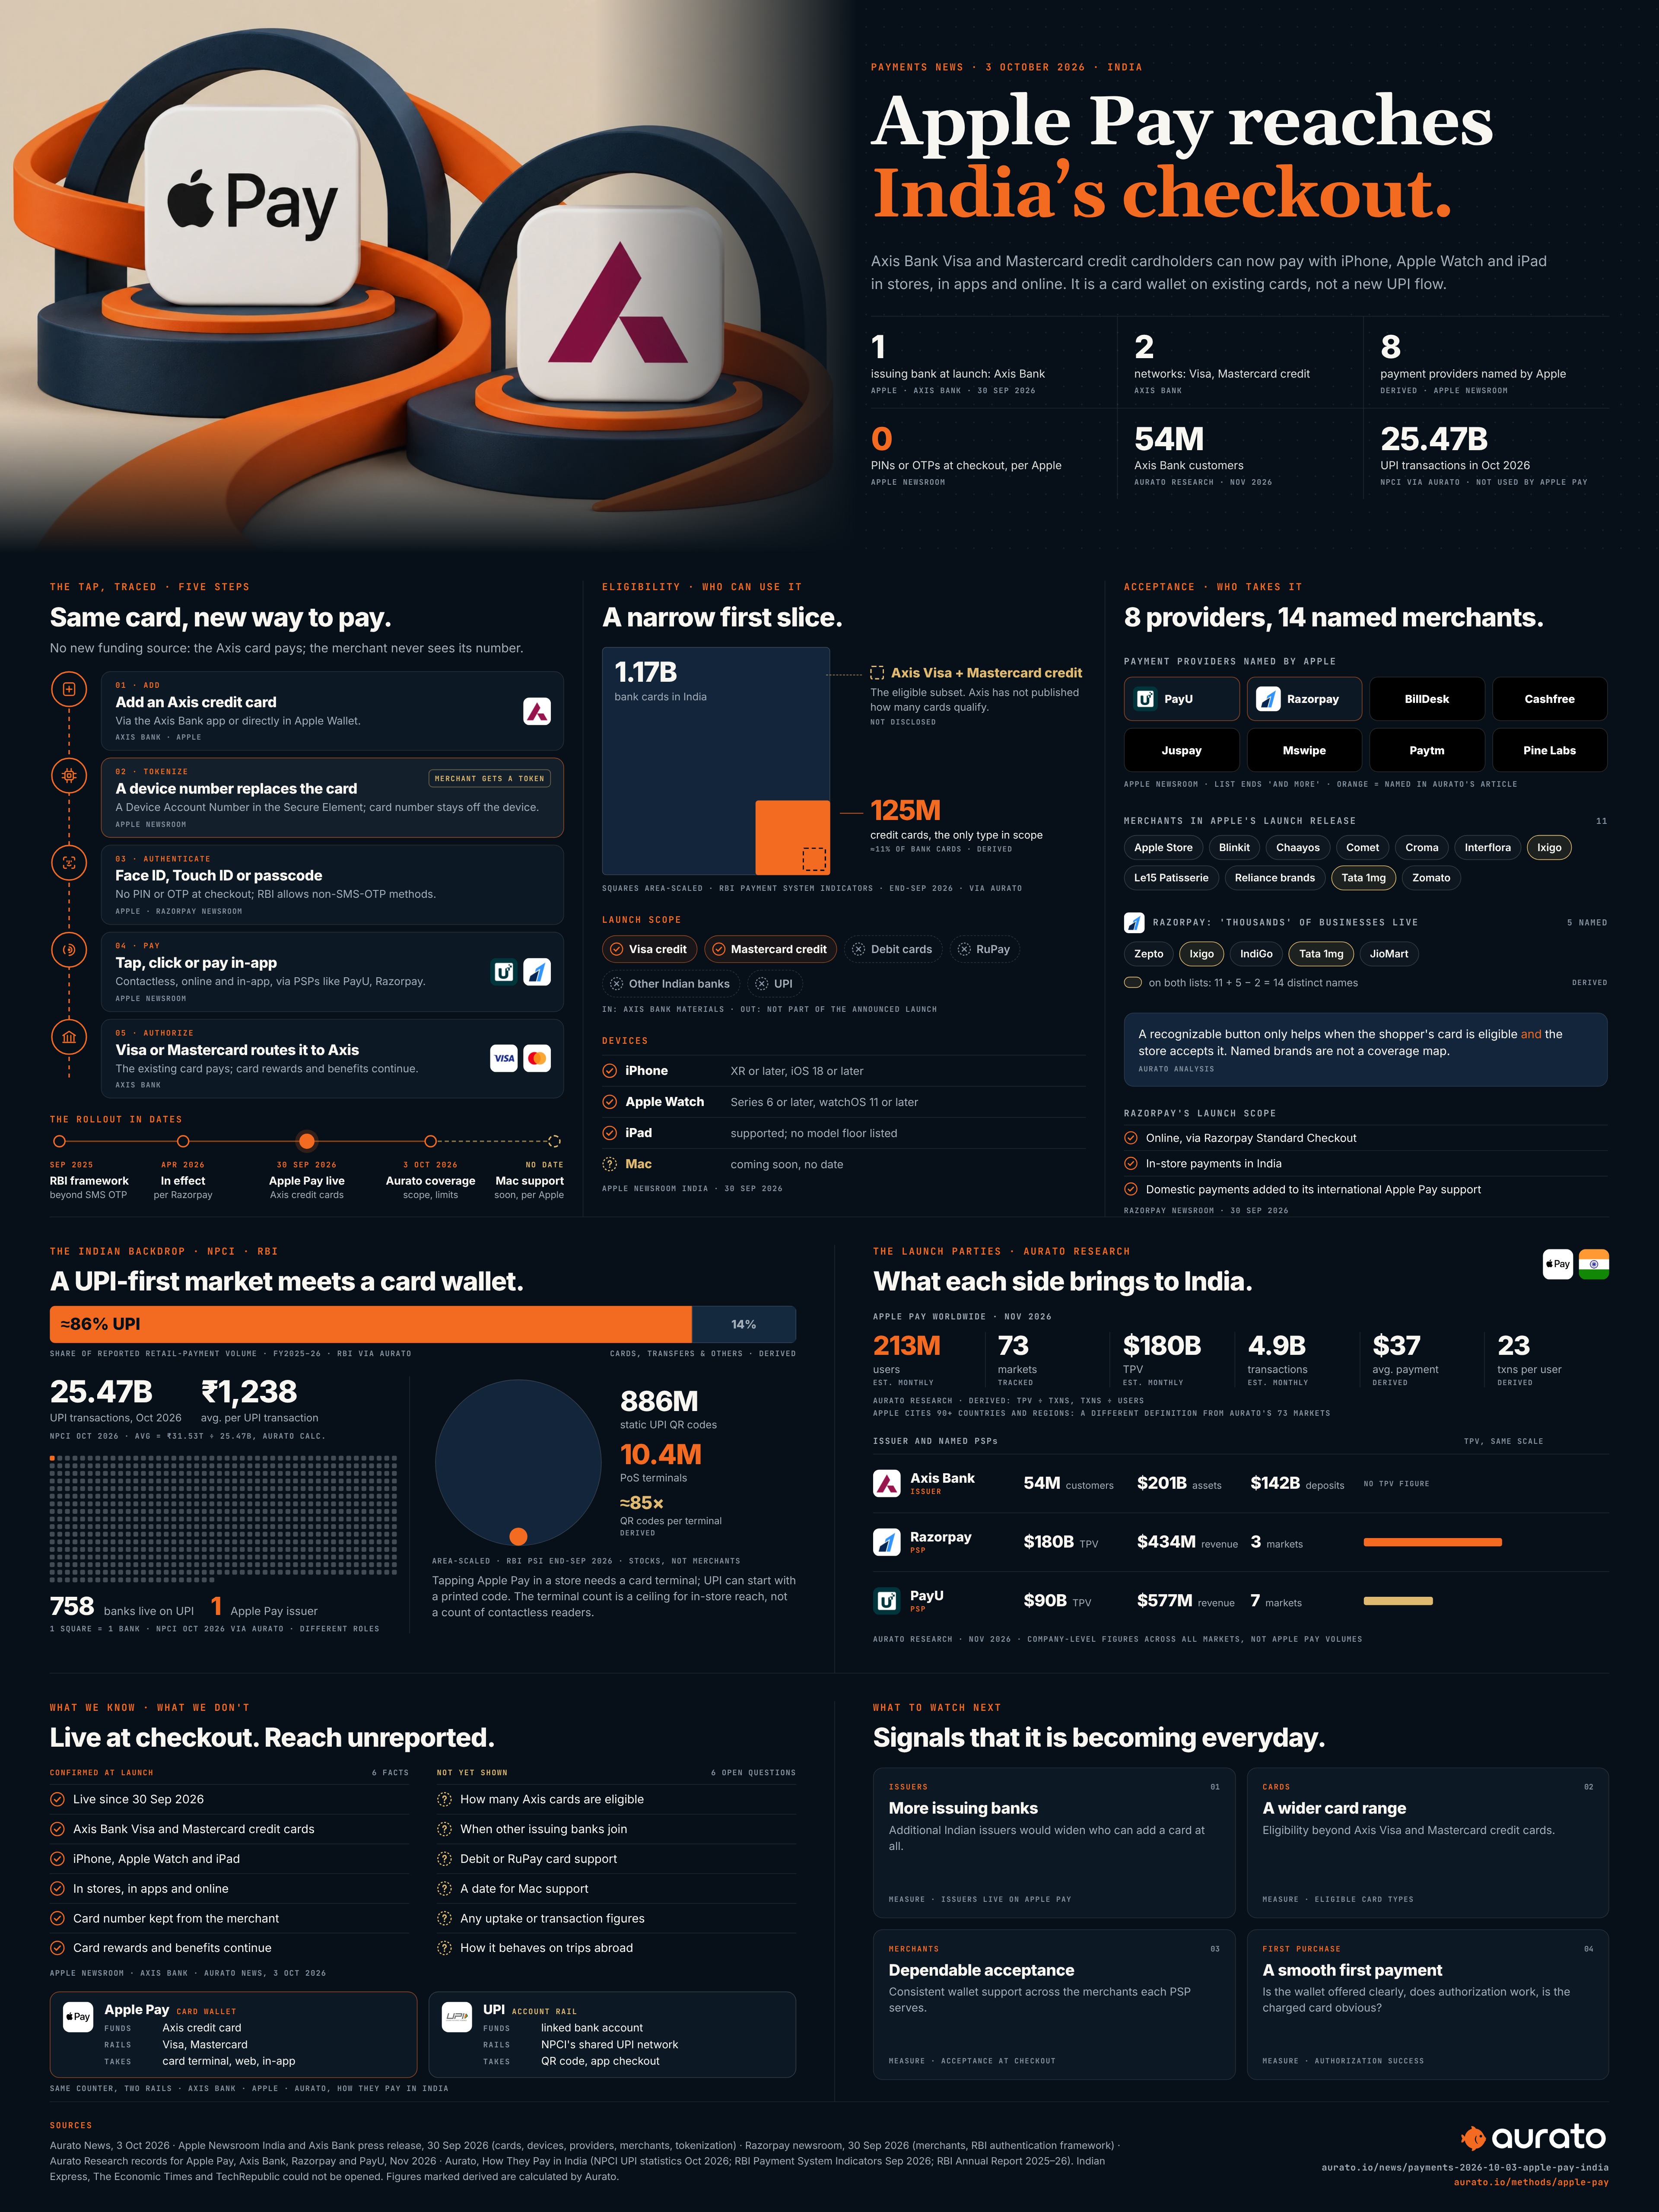
 Axis Bank customers can add supported credit cards through the bank’s app or Apple Wallet, then use the wallet at compatible contactless checkouts and supported online or in-app merchants. The launch covers
 Visa and
 Mastercard credit cards issued by the bank.
Apple names payment providers including  PayU and
 Razorpay among the merchant-integration partners. Its launch materials also name retail and online businesses accepting the wallet. The Economic Times examines the practical card-wallet experience for shoppers, including travel and overseas use.
Why it matters
The interesting development is a new way to use an existing card at checkout. For an eligible customer, choosing a wallet can change the interaction with a terminal or online payment screen without requiring a new source of funds.
Merchant availability and card eligibility will determine how useful the launch feels. A recognisable payment button is valuable only when the customer’s own card works and the store accepts it. The practical opportunity for PSPs is to make that experience consistent across the merchants they serve.
What remains limited
This launch does not establish support for every Indian bank or card. Axis Bank’s materials identify its eligible Visa and Mastercard credit cards. Apple describes support for specific devices and software versions, with Mac availability still forthcoming. The announced card-wallet service should not be presented as a new  UPI payment flow.
Axis Bank says existing card rewards and benefits continue. It also describes tokenisation: a device-specific account number supports payment while the actual card number is kept from the merchant. Customers still need an eligible card and a supported acceptance point.
What to watch
The next useful signals are additional issuing banks, a wider range of eligible cards and reliable merchant coverage. Those developments would show whether the initial launch is becoming an everyday option for more customers.
Look beyond a list of brand names to the experience at an actual checkout: whether the wallet is offered clearly, whether authorisation works and whether the customer understands which card is being charged. A smooth first purchase will matter more than a broad availability claim.