A domestic connection moves closer
 The People's Bank of China has approved
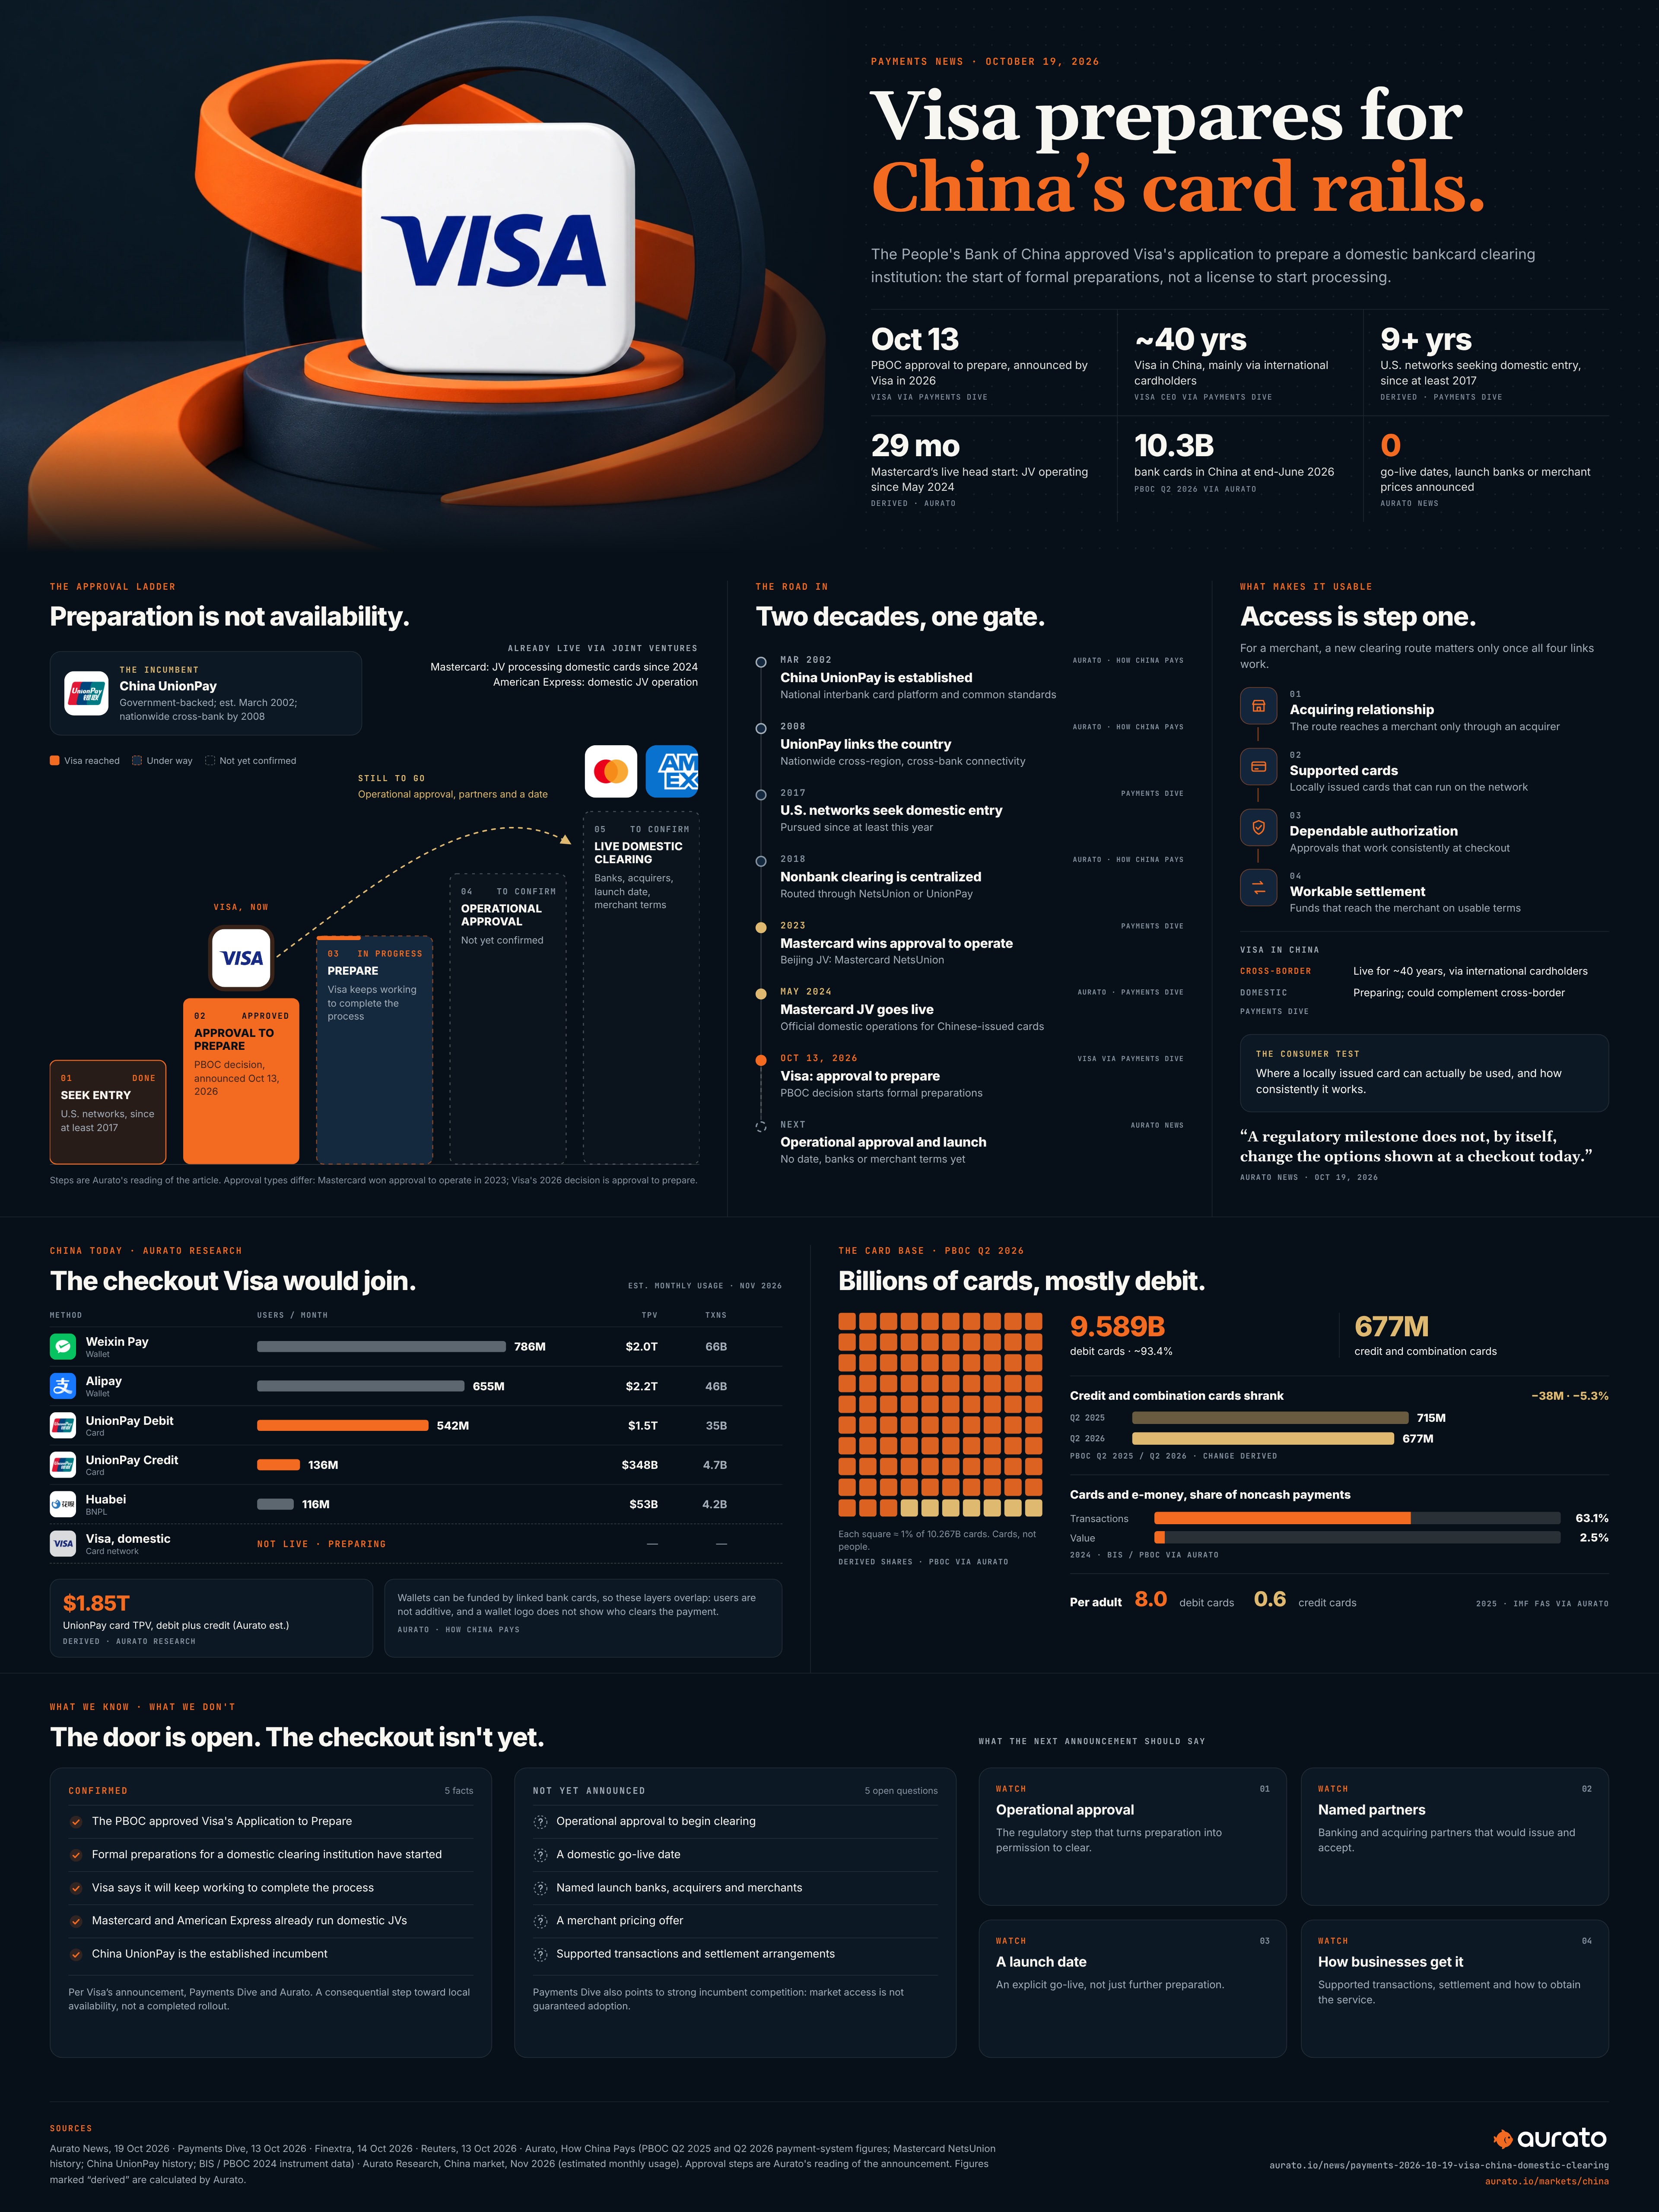
 Visa's Application to Prepare. The company describes this as the start of formal preparations for a domestic bankcard clearing institution. It explicitly says it will continue working to complete the process before beginning operations.
Payments Dive reports that domestic services could complement the network's existing cross-border business. Its coverage describes Visa's long-standing presence through international cardholders, rather than suggesting that this announcement marks the company's first involvement in  China.
Finextra places the decision in the wider opening of China's card market to overseas networks. Its report notes that  Mastercard began domestic processing through a joint venture in 2024, while
 American Express also has a joint-venture operation.
Market access needs a usable payment journey
For a merchant, an additional clearing route would matter only when it becomes available through an acquiring relationship, with supported cards, dependable authorisation and workable settlement. The headline opens a possibility; integration is what would eventually make it useful.
For consumers, the meaningful test would be where a locally issued card can actually be used and how consistently it works. A regulatory milestone does not, by itself, change the options shown at a checkout today.
Preparation is not availability
Visa's announcement does not give a domestic go-live date, name launch banks or merchants, or set out a merchant pricing offer. It promises further work toward operations, rather than an immediately orderable service.
Payments Dive also points to strong incumbent competition, including  China UnionPay. Access to the market should therefore not be confused with guaranteed adoption or a measured commercial result.
The next announcement should be concrete
Watch for confirmation of operational approval, named banking and acquiring partners, and an explicit launch date. Those would help distinguish a prepared business from a payment option merchants can enable.
The strongest follow-up would explain supported transactions, settlement arrangements and how businesses obtain the service. Until then, treat this as a consequential step toward local availability—not a completed rollout.