A familiar method at a major retail checkout
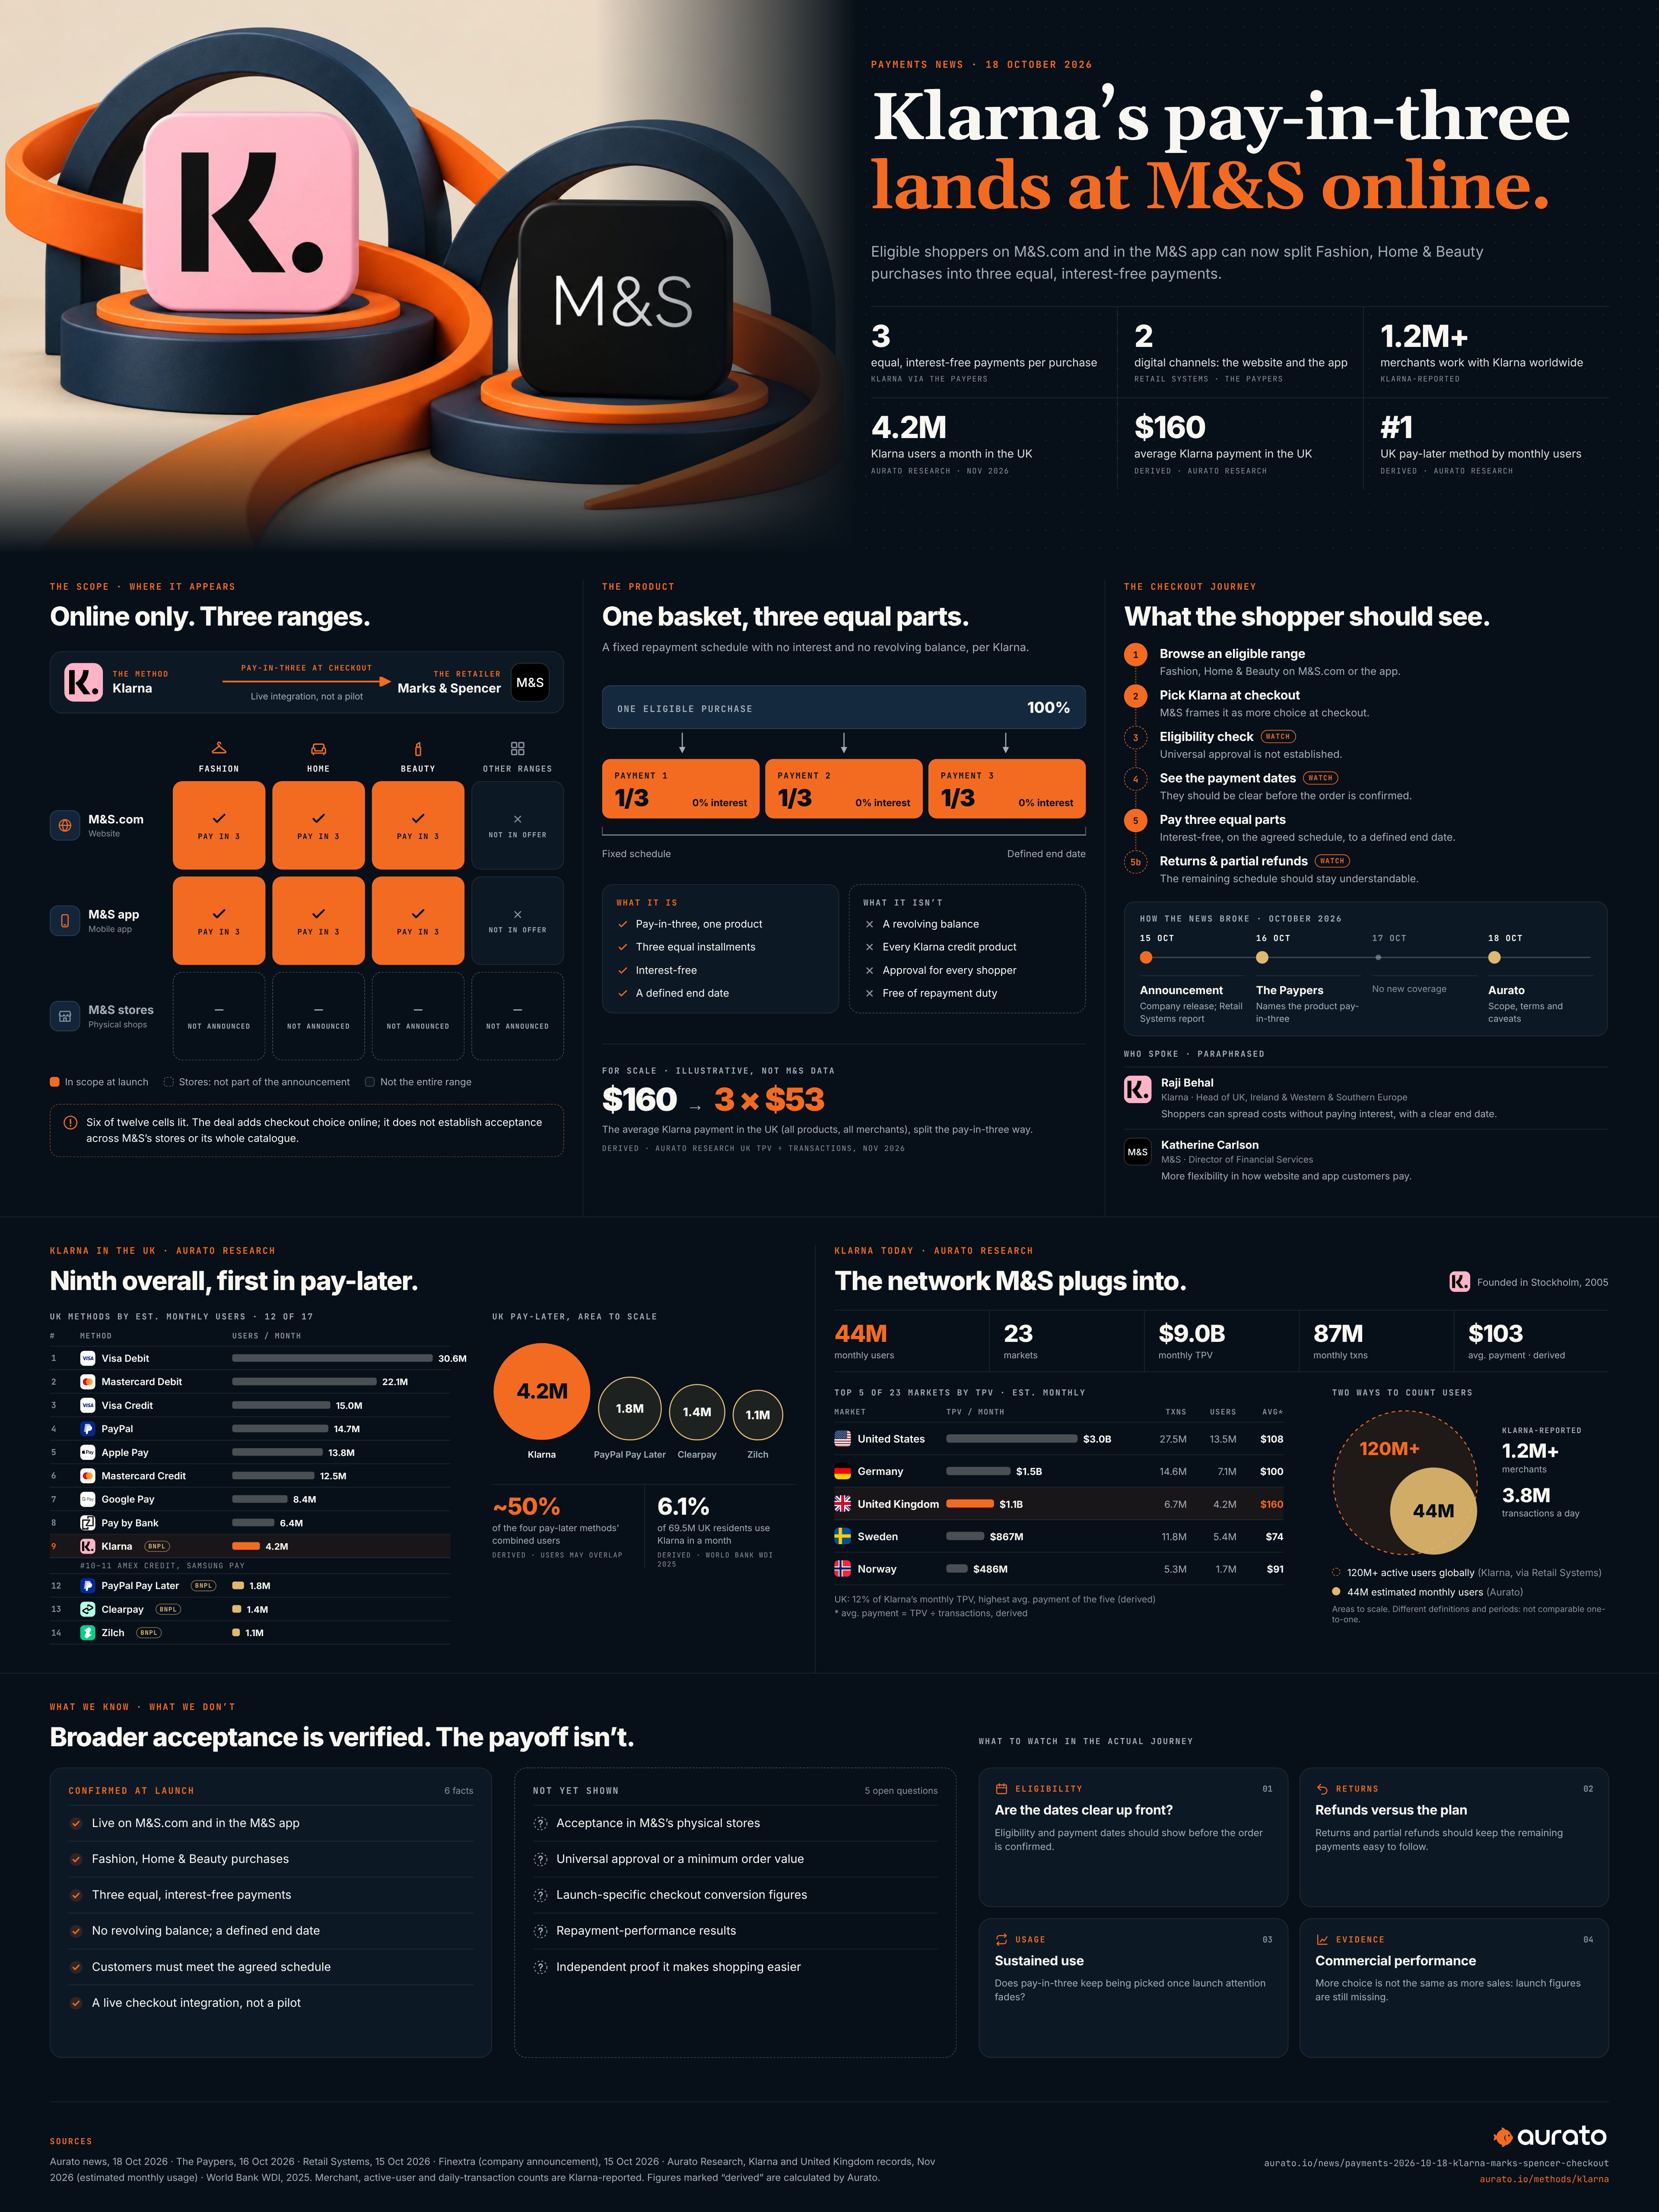
 Klarna is now a payment option for eligible purchases in M&S’s Fashion, Home & Beauty offer online. The launch introduces a live checkout integration, not a future pilot: shoppers can select the method on the website or in the retailer’s app.
The Paypers identifies the option as pay-in-three. It describes equal payments on a defined schedule with no revolving balance. That makes the specific product being offered important: the announcement is not a promise that every Klarna financing option is available at M&S.
Retail Systems reports that M&S frames the addition as greater choice at checkout. Its coverage confirms the category restriction and digital-channel focus, rather than presenting the agreement as acceptance throughout the retailer’s stores and product catalogue.
Distribution makes a payment method useful
Payment-method adoption is not just about whether shoppers recognise a logo. It also depends on whether they can use the method at a retailer they already visit, inside a checkout they understand. A named merchant launch makes that distribution tangible.
For the retailer, the opportunity is a different way to complete the same purchase. A useful integration needs clear eligibility, repayment information and order handling. Merchants should distinguish more customer choice from an assumed sales increase.
Interest-free does not remove the repayment schedule
The offer is described as interest-free, but the reporting does not say purchases become free of repayment obligations. Retail Systems explicitly notes that customers must meet their agreed schedule. Its article does not establish universal approval, a minimum order value or terms for every individual customer.
Neither the announcement nor The Paypers’ coverage provides launch-specific conversion figures or repayment-performance results. Claims that the addition will make shopping easier remain the companies’ stated objective, not an independently measured outcome.
What to watch in the actual journey
Watch how clearly the checkout explains eligibility and payment dates before an order is confirmed. Returns and partial refunds are another useful test: the shopping journey and the remaining payment schedule should stay understandable together.
For the wider market, sustained use and dependable order and repayment handling will matter most. Broader acceptance is verified; improved commercial performance still needs evidence.
Related
Sources
- Klarna launches on M&S.com to bring flexible payments to Fashion, Home & Beauty customersKlarna Group plc (via Public Technologies)
- Klarna at M&S checkoutThe Paypers
- Klarna partners with M&S for BNPL on website and appRetail Systems