One provider for more of the checkout
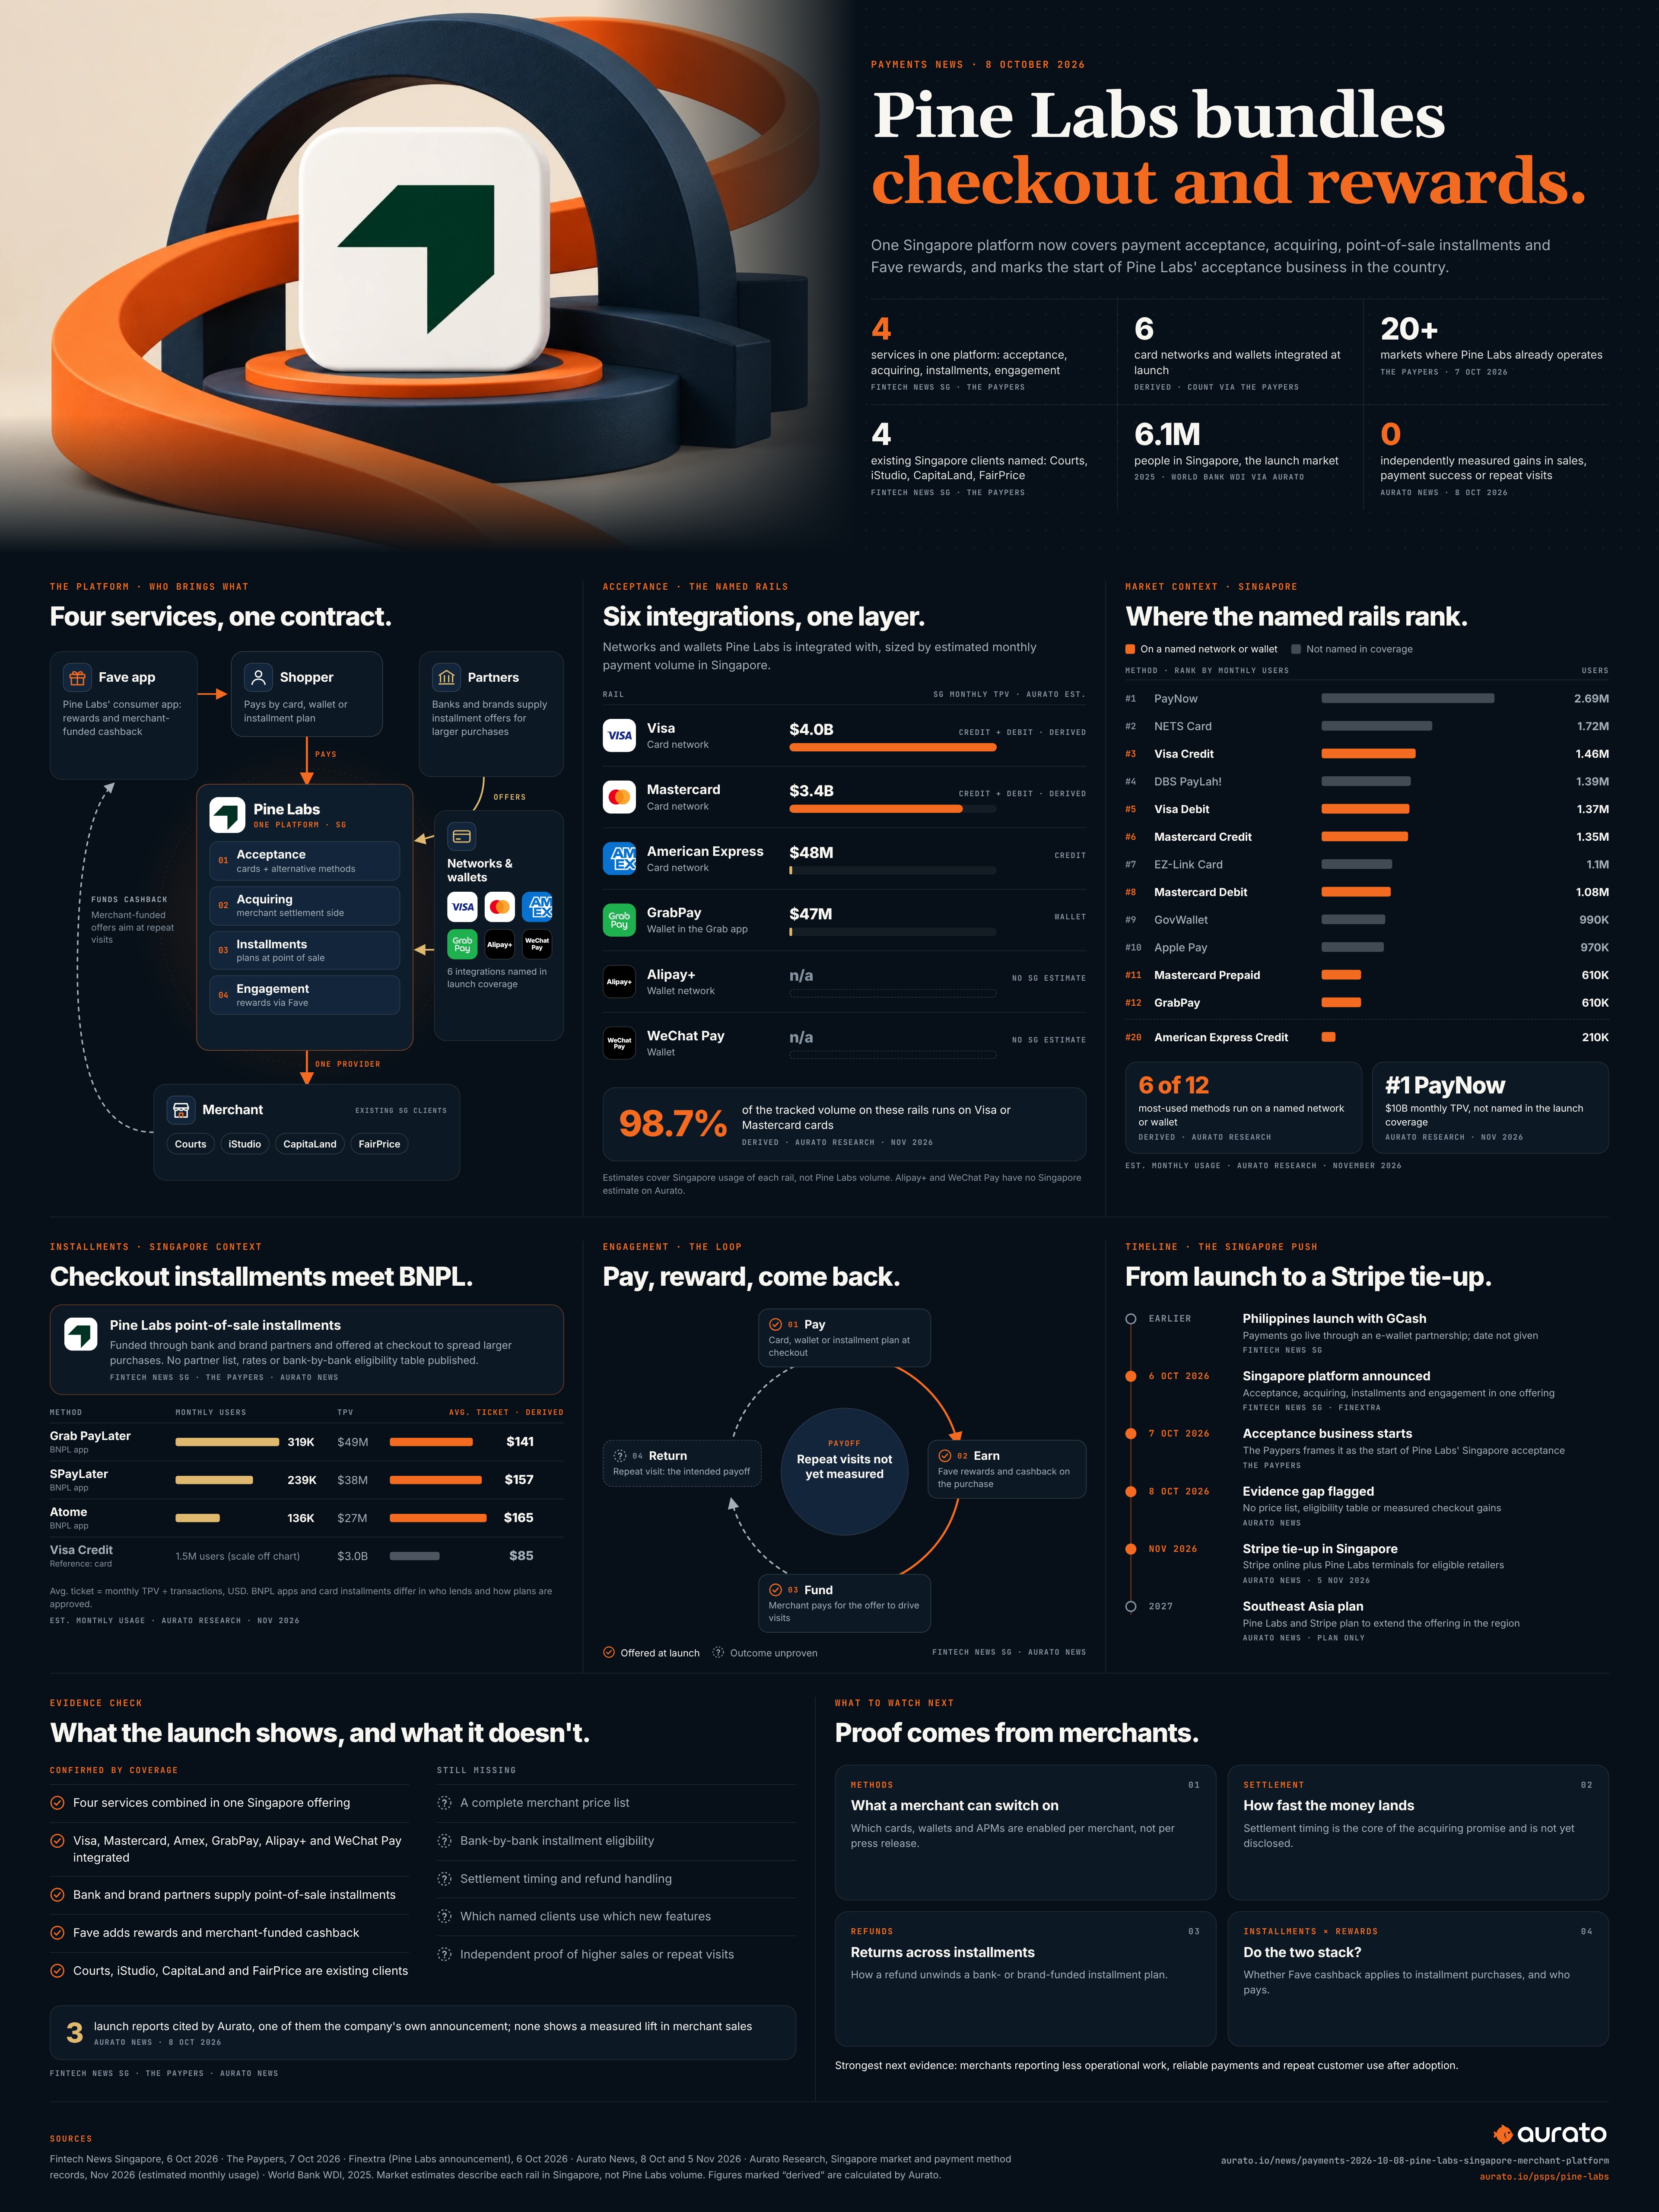
 Pine Labs is bringing several merchant services together in
 Singapore: accepting payments, acquiring, instalment plans and customer engagement. The company presents a consolidated offering for businesses that would otherwise manage these functions across separate providers.
Fintech News Singapore reports support for networks including  Visa,
 Mastercard and
 American Express, plus payment services such as
 GrabPay. Bank and brand partners supply instalment offers at the point of sale. Fave, the company’s consumer payments and engagement app, provides rewards and merchant-funded cashback.
This is a new combination of services in a market where Pine Labs already has customers. The company names Courts, iStudio, CapitaLand and FairPrice among its Singapore clients. That customer list should not be read as confirmation that every named business has adopted every element of the new platform.
Why merchants should care
A payment provider increasingly competes on what happens around the transaction. Bringing acceptance, instalments and rewards together could reduce the work of connecting systems, reconciling activity and managing several vendors. For a retailer, the value depends on whether those tools actually work together in daily operations.
For customers, flexibility at checkout and a reason to return are different benefits. A clear instalment offer can help with a larger purchase; a relevant reward can encourage another visit. Combining them will be useful only if the experience stays easy to understand and does not slow payment.
What still needs checking
The announcement does not set out a complete merchant price list, an independently measured checkout improvement or a bank-by-bank instalment eligibility table. The Paypers describes the integrated offering and regional expansion, but provides no evidence that the rollout has already increased merchants’ sales.
What to watch next
Watch the practical details: which methods a merchant can enable, settlement timing, refund handling and how instalments interact with rewards. A unified platform should make these easier to manage, rather than simply place more features behind one contract.
The strongest next evidence would be merchants explaining what changed after adoption: less operational work, reliable payments and repeat customer use. Those outcomes would say more than a launch claim about simplifying commerce.